Procurement
Purchase order vs goods receipt note: why quantity mismatches drain working capital
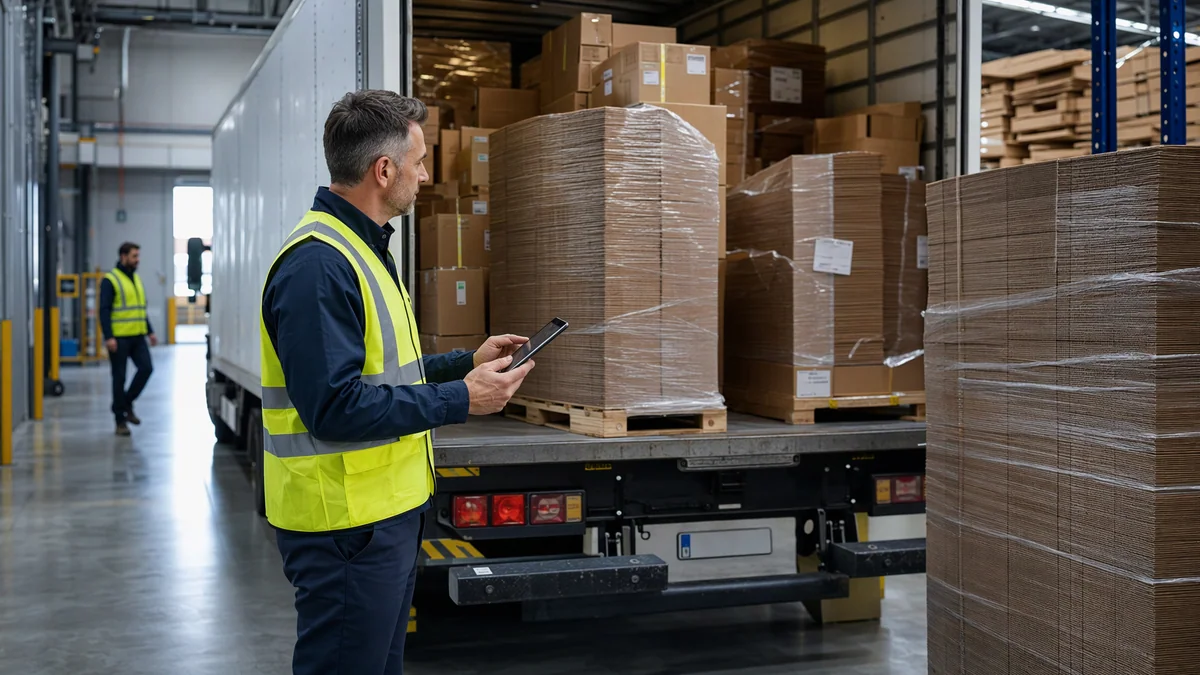
How do quantity mismatches between purchase orders and goods receipt notes create hidden working capital losses?
Quantity mismatches between purchase orders and goods receipt notes drain working capital when finance teams pay vendor invoices based on ordered quantities rather than verified physical receipts. Without automated three-way matching, companies routinely overpay for short shipments, pay unapproved unit price escalations, and lose input tax credit on damaged or returned goods. Enforcing automated tolerances between the PO, gate-inward GRN, and vendor tax invoice protects operational liquidity.
Key takeaways
- A Purchase Order is a commercial commitment; a Goods Receipt Note is legal evidence of physical delivery and title transfer.
- Paying supplier bills against PO quantities rather than verified GRN counts causes unrecovered cash leakage on short shipments.
- Three-way matching must verify item code, quantity received, unit price, and GST tax classification before payment voucher creation.
- Automating quantity-tolerance thresholds allows minor allowable bulk variances while blocking unauthorized over-billings.
The business scenario: the phantom ₹3.4 lakh packaging overpayment
Apex Consumer Goods manufactures packaged spices and food products in Gujarat, purchasing roughly ₹40 lakh worth of multi-layer printed pouches, corrugated shippers, and labels every month across six packaging suppliers. In their historical workflow, the purchase manager issued Purchase Orders (POs) by emailing PDF documents created in spreadsheets.
When trucks arrived at the warehouse gate, the receiving supervisor stamped the supplier's physical delivery challan with a generic rubber stamp reading Received Subject to Verification. The physical goods were moved straight to storage racks. Two weeks later, the supplier's formal GST tax invoice arrived at the accounts department. The accounts clerk opened the PO file, confirmed that the total billed rate matched the authorized PO, and processed a payment voucher for ₹8,50,000.
It was only during the annual physical inventory count six months later that external auditors discovered a shortfall of 42,000 printed pouches. The factory had received only 958,000 pouches instead of the billed 1,000,000. Over eighteen consecutive deliveries, the supplier had delivered 4% to 5% short due to roll-end printing wastage, but had billed 100% of the ordered quantity every single time. Apex had paid ₹3,40,000 for packaging materials that never physically entered the plant.
Why the problem occurred: the gap between PO commitment and physical GRN
This operational breakdown happens because many growing companies treat a Purchase Order (PO) and a Goods Receipt Note (GRN) as interchangeable administrative paperwork, rather than two fundamentally distinct legal and operational instruments:
- The Purchase Order (PO): Represents an intent to buy at agreed commercial terms. It establishes the item specification, contracted price per unit, delivery schedule, payment terms, and applicable GST rates. It does not prove that goods exist or that they have been delivered.
- The Goods Receipt Note (GRN): Represents legal evidence of delivery, physical custody, and title transfer. It records what physically crossed the threshold of the warehouse dock, including verified batch numbers, manufacturer dates, carton counts, and quality inspection results.
When accounts payable teams pay bills by comparing the vendor invoice solely against the PO, they are operating blind. They are paying for what was requested, not what was actually delivered.
The anatomy of three-way matching: PO vs GRN vs Invoice
To protect working capital, professional supply chain teams enforce three-way matching. In this internal control architecture, an Accounts Payable voucher cannot be authorized for payment until the ERP verifies complete mathematical alignment across three independent documents:
| Data element | Purchase Order (PO) | Goods Receipt Note (GRN) | Vendor Tax Invoice | Match criteria |
|---|---|---|---|---|
| Item code & SKU | PO-FG-102 (Pouch) | PO-FG-102 (Pouch) | PO-FG-102 (Pouch) | Exact match required |
| Quantity | 50,000 units ordered | 47,500 units accepted | 50,000 units billed | Invoice must not exceed GRN |
| Unit price | ₹4.20 per unit | — (Operational count) | ₹4.40 per unit | Invoice must not exceed PO |
| Taxes & HSN | HSN 3923 / 18% GST | — (Logistics check) | HSN 3923 / 18% GST | HSN and tax rates must match |
| Total liability | ₹2,47,800 | — | ₹2,59,600 | Billed amount adjusted to ₹2,35,410 |
In the worked example above, three-way matching catches two distinct leakages: the vendor billed for 50,000 units despite delivering only 47,500 units, and attempted an unapproved ₹0.20 price escalation per unit. Automated matching immediately cuts the authorized payable liability from ₹2,59,600 down to ₹2,35,410, saving ₹24,190 on a single transaction.
Step-by-step process: implementing a watertight P2P control workflow
01Issue version-controlled purchase orders from ERP
Create POs with pre-locked prices from approved supplier rate contracts. Ensure POs require digital sign-off based on financial delegation thresholds.
02Enforce digital gate entry logging
When the transporter arrives, security logs the vehicle number, transporter LR (Lorry Receipt) number, and gross weight at the gate before granting bay access.
03Conduct blind count or verified GRN tallying
Warehouse personnel count physical boxes and input actual counts into the ERP GRN module. The system immediately flags partial deliveries or shortages against the open PO line.
04Perform mandatory QC inspection before stock release
Quality personnel inspect samples for thickness, burst pressure, and seal integrity. Damaged or rejected items are segregated into quarantine and generate a rejection note.
05Automate invoice reconciliation and tolerance checks
When the vendor bill arrives, the ERP matches the invoice against the accepted GRN quantity and authorized PO rate. Any deviation beyond pre-configured tolerances triggers an AP hold.
Accounting entries: how double-entry records GRN and purchase variances
A robust ERP architecture decouples physical inventory receipt from the arrival of the vendor's tax bill using a Goods Received Not Invoiced (GRNI) suspense account:
1. At the time of Goods Receipt (GRN Posting):
Debit: Inventory - Raw Materials (47,500 units @ ₹4.20) = ₹1,99,500
Credit: GRNI Suspense Clearing Account = ₹1,99,500
*(Raw material stock is physically and financially available for factory consumption immediately)*
2. When Vendor Tax Invoice is Approved (3-Way Matched):
Debit: GRNI Suspense Clearing Account = ₹1,99,500
Debit: Input CGST (9%) = ₹17,955
Debit: Input SGST (9%) = ₹17,955
Credit: Accounts Payable - Packaging Vendor = ₹2,35,410
*(GRNI suspense clears to zero; vendor ledger reflects exact liability for received goods only)*
3. Handling Unavoidable Bulk Price Variances (e.g. Approved Commodity Surges):
If an authorized price variance is approved, the difference between the PO rate and the invoice rate posts to a dedicated Purchase Price Variance (PPV) expense account, keeping raw material standard inventory valuation clean.
Common mistakes in procurement and accounts payable management
- Verbal and WhatsApp purchase commitments: Allowing department heads to order emergency materials without a system PO guarantees price disputes and invoice surprises at month-end.
- Accepting deliveries without PO reference: Receiving goods on the dock without an active PO number creates orphaned inventory that cannot be matched to commercial agreements.
- Paying based on vendor statements of account: Paying suppliers against a periodic summary statement rather than verified individual bills invites duplicate payments and paid debit notes.
- Ignoring short-delivery Input Tax Credit (ITC) risks: Under Section 16(2)(aa) of the CGST Act, buyers can claim ITC only on goods actually received. Claiming ITC on billed but undelivered quantities invites statutory tax penalties.
How departments connect to safeguard purchasing liquidity
Procurement control is inherently cross-functional. An error at the dock immediately impacts the balance sheet:
Procurement Team: Negotiates long-term volume agreements and enters approved price lists into the ERP so purchase orders automatically pull contracted rates.
Warehouse & Dock Staff: Act as the first line of financial defence. By refusing to sign uninspected challans, they ensure the company takes legal custody of accepted goods only.
Quality Control: Fast-tracks testing so that supplier rejections are flagged before invoices are submitted, generating automated debit notes and return gate passes.
Finance & Accounts: Releases payments strictly according to bill-by-bill 3-way matching rules, taking full advantage of vendor early-payment cash discounts.
How Naffo automates procurement and three-way matching
Naffo's procurement management suite eliminates manual invoice checking. When purchase orders are created, rates are locked against vendor contracts with automatic GST calculation. At the warehouse, warehouse operators use the mobile-friendly GRN interface to record received quantities, batch numbers, and QC results.
When a vendor invoice is uploaded, Naffo's Three-Way Matching Engine automatically performs line-by-line verification against the accepted GRN. If the quantity billed exceeds the GRN, or if the unit price exceeds the PO tolerance, the invoice is automatically placed on an Exception Hold with an instant notification to the procurement manager.
Furthermore, Naffo integrates with GSTR-2B inward tax streams, ensuring that your accounts payable team only approves vendor payments when the invoice has also been successfully filed by the supplier on the GST portal.
Frequently asked questions
What is an acceptable quantity tolerance between a PO and a GRN in manufacturing?
In discrete manufacturing, tolerances are typically 0%. However, in bulk commodities, liquids, and agricultural produce, shrinkage and weighing discrepancies often justify a pre-configured quantity tolerance between ±1% and ±3%. The ERP should allow receiving within tolerance while automatically adjusting invoice liabilities.
Can a company legally deduct short delivery amounts without a vendor debit note?
Yes. Under Indian commercial practice, the buyer approves the invoice only for the verified GRN quantity and issues an official Goods Inward Discrepancy Note or Debit Note detailing the short quantity and deduction amount prior to payment settlement.
How does 3-way matching impact GSTR-2B Input Tax Credit reconciliation in India?
Under the CGST Act, a registered taxpayer is only eligible to claim Input Tax Credit on goods that have actually been received. Three-way matching ensures that the invoice value booked in your purchase register matches the physical goods received, preventing fraudulent or disallowed ITC claims.
This page also answers
- What is the difference between a purchase order and a goods receipt note?
- How does 3-way matching prevent accounts payable overpayments?
- What accounting entries record a purchase price variance between PO and invoice?
Connected System
How Naffo handles these workflows
Purchase Order & Approval Management
Manage purchase requisitions, supplier RFQ comparisons, and role-based PO approvals with strict price contracts.
Gate Inward & Goods Receipt (GRN)
Log physical delivery count, batch details, and QC inspection status at the warehouse gate.
Three-Way AP Bill Matching
Automated line-by-line reconciliation matching PO rates and GRN quantities against incoming vendor invoices.
How to evaluate your software budget
Naffo follows a transparent, evidence-based software evaluation model: never commit to an ERP budget that isn't justified by verified operational savings. Estimate avoided administrative hours, reduced inventory write-offs, and prevented batch waste before setting a recurring budget.
Naffo STANDARD
Tailored for Manufacturing, trading, and FMCG businesses issuing 50+ purchase orders monthly.
₹24,000 to ₹36,000 / year
Based on team size, transaction volume, and module scope.
Included in Evaluation:
- 14-day full-featured test workspace
- Master data import (Tally, Excel)
- Personal onboarding & workflow mapping
- Zero vendor lock-in with full data export
No pressure. We discuss your workflows first.
Industry Offerings
Tailored ERP solutions from Naffo
Naffo Dairy ERP
Complete milk procurement, Fat/SNF testing, chilling center logs, tanker intake, standardization, and farmer settlements.
Food Manufacturing ERP
Multi-level recipes, work orders, batch yield, dynamic by-product allocation, and FSSAI batch recall traceability.
Wholesale & Distribution ERP
Distributor portal, multi-depot stock, route dispatching, OTP-verified receiving, and debtor aging recovery.
Ready to connect your business operations?
Experience how Naffo replaces disjointed spreadsheets, billing tools, and manual stock logs with one integrated ERP.
Related answers
ERP selection
How to evaluate accounting and operations software for distributors
How should a distributor or wholesale trader in India evaluate accounting and operations software?
Cash flow
How should distributors and manufacturers reconcile payments?
How should distributors and manufacturers reconcile payments and plan cash flow?
GST and accounting
How should manufacturers and distributors reconcile GSTR-2B and IMS?
How should manufacturers and distributors prepare GSTR-2B and IMS reconciliation?