Inventory
FIFO vs weighted average costing: which inventory method fits Indian manufacturing?
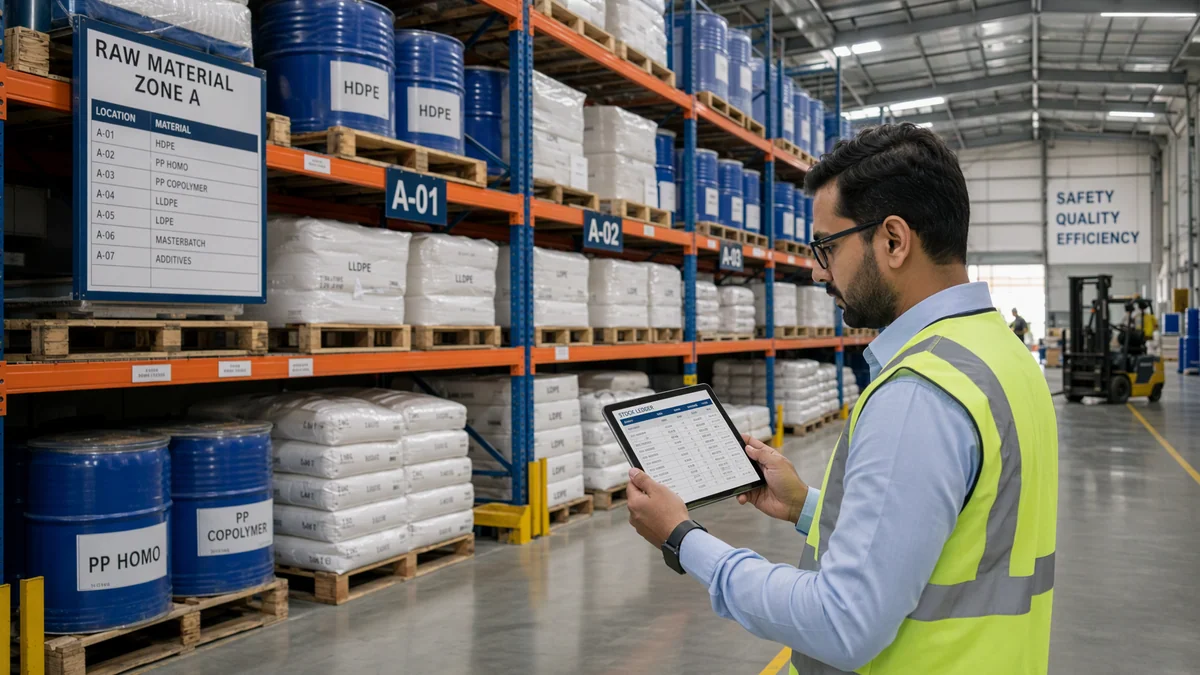
How do FIFO and weighted average costing differ in their impact on Indian manufacturing profits, GST audits, and balance sheet inventory valuation?
FIFO (First-In, First-Out) assumes the oldest inventory batches are consumed first, matching current higher replacement costs with unsold closing stock during inflationary periods. Weighted Average Costing (WAC) smooths out procurement price volatility by recalculating an average unit rate after every purchase. Both methods comply with Indian Accounting Standard AS-2 and Ind AS 2, but FIFO yields higher reported profits during rising price cycles, whereas WAC provides stable Cost of Goods Sold (COGS) in volatile commodity environments.
Key takeaways
- Both FIFO and Weighted Average Costing are legally permitted under Indian AS-2, Ind AS 2, and Section 145A of the Income Tax Act.
- LIFO (Last-In, First-Out) is strictly prohibited under Indian tax laws and GAAP standards.
- In inflationary markets, FIFO reports higher closing stock value, lower Cost of Goods Sold, and higher taxable net profit.
- Weighted Average Costing prevents erratic month-to-month margin spikes for manufacturers purchasing commodities subject to weekly price fluctuations.
The business scenario: how commodity swings created a ₹7.2 lakh tax surprise
Consider a precision plastic injection moulding business, Sigma Polymers, operating in Pune, Maharashtra. The company consumes roughly 30 metric tons of polypropylene (PP) granules per month. Over the past twelve months, global crude oil fluctuations caused virgin PP polymer prices to swing wildly between ₹88 per kg in April, ₹114 per kg in August, and ₹98 per kg in December.
Sigma's accounts team historically used simple manual spreadsheet spreadsheets to value closing stock at the latest invoice price received at year-end (₹112/kg). When their tax audit commenced under Section 44AB of the Income Tax Act, the chartered accountant rejected their inventory schedule immediately. By using the peak latest price rather than a recognized cost formula, Sigma had inflated their closing stock value by ₹7.2 lakh, which in turn artificially inflated their taxable net profit and produced an unexpected ₹1.8 lakh advance tax demand.
Selecting the correct valuation methodology—and enforcing it automatically inside your ERP—is not merely an academic accounting debate; it directly dictates your reported gross margins, your working capital financing limits, and your statutory tax liabilities.
The statutory framework: AS-2, Ind AS 2, and Indian tax law
In India, inventory valuation is governed by strict statutory accounting standards. Whether your business is a private limited manufacturing firm or an SME proprietorship, you must comply with Accounting Standard 2 (AS-2: Valuation of Inventories) or Indian Accounting Standard 2 (Ind AS 2):
- The Lower of Cost and Net Realizable Value (NRV): Inventories must be valued at the lower of historical cost and net realizable value (estimated selling price in the ordinary course of business less completion and selling costs).
- Permitted Cost Formulas: For non-interchangeable items (e.g. specialized capital machinery), specific identification is required. For interchangeable bulk items, the standard explicitly permits only two formulas: FIFO (First-In, First-Out) or Weighted Average Costing.
- LIFO Prohibition: The Last-In, First-Out (LIFO) formula is strictly prohibited by both AS-2 and the Indian Income Tax Department because it permits companies to manipulate taxable income during inflationary cycles.
Mathematical breakdown: FIFO vs Weighted Average in action
To see how these two methods diverge in practice, let us trace a typical month of raw material transactions for a manufacturing plant purchasing industrial resin:
| Date | Transaction | Quantity (kg) | Unit rate (₹) | Total value (₹) | Cumulative stock (kg) |
|---|---|---|---|---|---|
| 01 Oct | Opening balance | 1,000 | ₹100.00 | ₹1,00,000 | 1,000 |
| 08 Oct | Purchase Batch #1 | 2,000 | ₹110.00 | ₹2,20,000 | 3,000 |
| 15 Oct | Production Issue #1 | 2,500 | — | — | 500 |
| 22 Oct | Purchase Batch #2 | 2,500 | ₹120.00 | ₹3,00,000 | 3,000 |
| 28 Oct | Production Issue #2 | 1,800 | — | — | 1,200 |
Total available stock was 5,500 kg costing ₹6,20,000. Total production consumption was 4,300 kg, leaving 1,200 kg of closing inventory. Notice how the two methods allocate this value:
| Metric | FIFO Method | Weighted Average (WAC) | Variance & Impact |
|---|---|---|---|
| Cost of Issue #1 (2,500 kg) | ₹2,65,000 (1000@100 + 1500@110) | ₹2,66,667 (2500 @ ₹106.67) | +₹1,667 under WAC |
| Cost of Issue #2 (1,800 kg) | ₹2,11,000 (500@110 + 1300@120) | ₹2,12,000 (1800 @ ₹117.78) | +₹1,000 under WAC |
| Total COGS for month | ₹4,76,000 | ₹4,78,667 | FIFO COGS is ₹2,667 lower |
| Closing stock value (1,200 kg) | ₹1,44,000 (1200 @ ₹120.00) | ₹1,41,333 (1200 @ ₹117.78) | FIFO inventory is ₹2,667 higher |
| Reported gross profit | Higher by ₹2,667 | Lower by ₹2,667 | FIFO yields higher reported profit |
In an inflationary environment where raw material prices rise from ₹100 to ₹120, FIFO assigns the cheaper early costs to production issues and leaves the expensive recent costs in closing inventory. This results in a higher balance sheet asset value and higher taxable profit. Weighted Average Costing blends the layers, dampening the spike.
Which method should your business choose?
The choice between FIFO and Weighted Average depends on your industry, physical handling, and raw material volatility:
Choose FIFO if:
- You manufacture food, pharmaceuticals, chemicals, or dairy products where physical stock strictly moves under FEFO (First-Expiry, First-Out) or FIFO to prevent spoilage.
- Your products have distinct batch numbers where material traceability from supplier to finished product must be maintained.
- You want closing stock on your balance sheet to closely reflect current replacement market values for bank working-capital drawing power.
Choose Weighted Average Costing (WAC) if:
- You handle bulk commodities that physically mix together in silos, tanks, or heaps (e.g. grain, cement, sand, vegetable oils, bulk chemicals).
- Your raw material prices fluctuate violently on a daily or weekly basis (e.g. scrap metal, cotton, raw polymers), and you want to prevent wild monthly swings in reported product cost.
- Your factory operators find it difficult or unnecessary to segregate identical raw materials by specific purchase lot.
The catastrophic impact of negative inventory on valuation
One of the most destructive operational issues in ERP systems is negative inventory—issuing goods in the software before the corresponding goods receipt note has been entered. When stock goes below zero in the system, both FIFO and Weighted Average algorithms completely break down:
Step-by-step process: setting up automated valuation in Naffo
01Define valuation method per inventory category
In organization settings, choose whether standard inventory lines calculate under Moving Weighted Average or FIFO. Batch-tracked items automatically preserve exact lot cost layers.
02Enforce negative inventory blocking
Activate strict physical stock controls in the stock policy engine. Prevent sales dispatches or production issues from posting if available warehouse location stock is insufficient.
03Capture landed costs in purchase receipts
Include freight, transit insurance, customs duties, and unloading charges directly into the Goods Receipt Note to establish true landed cost layers under AS-2 guidelines.
04Conduct periodic physical count reconciliations
Conduct rolling cycle counts or monthly stock verifications. Record variances through reason-coded adjustment vouchers that automatically adjust inventory valuation reserves.
How Naffo maintains real-time valuation integrity
Naffo incorporates an immutable, single-writer Stock Ledger (StockLedger) that records every physical movement with its associated unit cost and balance layer. Unlike systems that calculate valuation as a batch report at month-end, Naffo updates moving average and FIFO cost layers instantaneously upon every transaction.
When raw materials are issued to a manufacturing work order, Naffo automatically consumes the appropriate FIFO lot or applies the current location-specific weighted average rate. The resulting double-entry accounting voucher automatically debits Work-in-Progress and credits Raw Material Inventory, ensuring your financial balance sheet is perpetually synchronized with physical warehouse shelves.
Frequently asked questions
Can an Indian business change its inventory valuation method from WAC to FIFO?
Yes, an enterprise can change its accounting policy for inventory valuation if required by statute or if the change results in a more appropriate presentation of financial statements. However, under AS-1 and AS-2, the company must disclose the justification for the change and quantify its financial impact in the audited notes to accounts.
Does GST in India require inventory to be valued including or excluding Input Tax Credit?
Under Section 145A of the Income Tax Act, inventory valuation for income tax purposes follows the inclusive method (including taxes paid). However, for financial accounting under AS-2, GST paid on purchases is excluded from inventory cost provided the taxpayer is eligible to claim Input Tax Credit against output tax liabilities.
What happens if net realizable value (NRV) falls below the purchase cost?
Under AS-2, if the estimated selling price less completion and selling costs falls below original cost (for example due to physical damage or market obsolescence), the inventory must be written down to its NRV. The difference is recognized immediately as an expense in the Profit and Loss statement.
This page also answers
- Why is LIFO prohibited under Indian Accounting Standards and Income Tax laws?
- How does negative inventory distort FIFO and weighted average stock calculations?
- Which inventory costing method minimizes income tax liability in an inflationary market?
Connected System
How Naffo handles these workflows
Perpetual Inventory & Costing
Automated valuation engine supporting real-time FIFO and moving Weighted Average Costing per location.
Batch & Serial Tracking
Assigns unique batch IDs with date of manufacture, shelf-life expiry, and purchase unit rate.
General Ledger & Balance Sheet
Direct real-time posting of inventory additions, consumption, and month-end closing stock adjustments.
How to evaluate your software budget
Naffo follows a transparent, evidence-based software evaluation model: never commit to an ERP budget that isn't justified by verified operational savings. Estimate avoided administrative hours, reduced inventory write-offs, and prevented batch waste before setting a recurring budget.
Naffo STANDARD
Tailored for Manufacturers, chemical processors, engineering plants, and distributors managing multiple stock lots.
₹24,000 to ₹36,000 / year
Based on team size, transaction volume, and module scope.
Included in Evaluation:
- 14-day full-featured test workspace
- Master data import (Tally, Excel)
- Personal onboarding & workflow mapping
- Zero vendor lock-in with full data export
No pressure. We discuss your workflows first.
Industry Offerings
Tailored ERP solutions from Naffo
Naffo Dairy ERP
Complete milk procurement, Fat/SNF testing, chilling center logs, tanker intake, standardization, and farmer settlements.
Food Manufacturing ERP
Multi-level recipes, work orders, batch yield, dynamic by-product allocation, and FSSAI batch recall traceability.
Wholesale & Distribution ERP
Distributor portal, multi-depot stock, route dispatching, OTP-verified receiving, and debtor aging recovery.
Ready to connect your business operations?
Experience how Naffo replaces disjointed spreadsheets, billing tools, and manual stock logs with one integrated ERP.
Related answers
Costing & metrics
How to cost a manufactured food product correctly, including by-product allocation
How do you calculate the cost of a manufactured food product?
Costing & metrics
Yield, wastage and by-product formulas every food factory should track
What are the formulas for yield, wastage and by-product recovery in food manufacturing?
Business operations
The five-minute owner dashboard: run your business without doing everything yourself
How should a business owner manage a manufacturing business more efficiently?